Appraisal Waivers: You May Still Need a Property Check
· By the HomePilot team · Reviewed by a licensed loan officer · Company NMLS #2752340
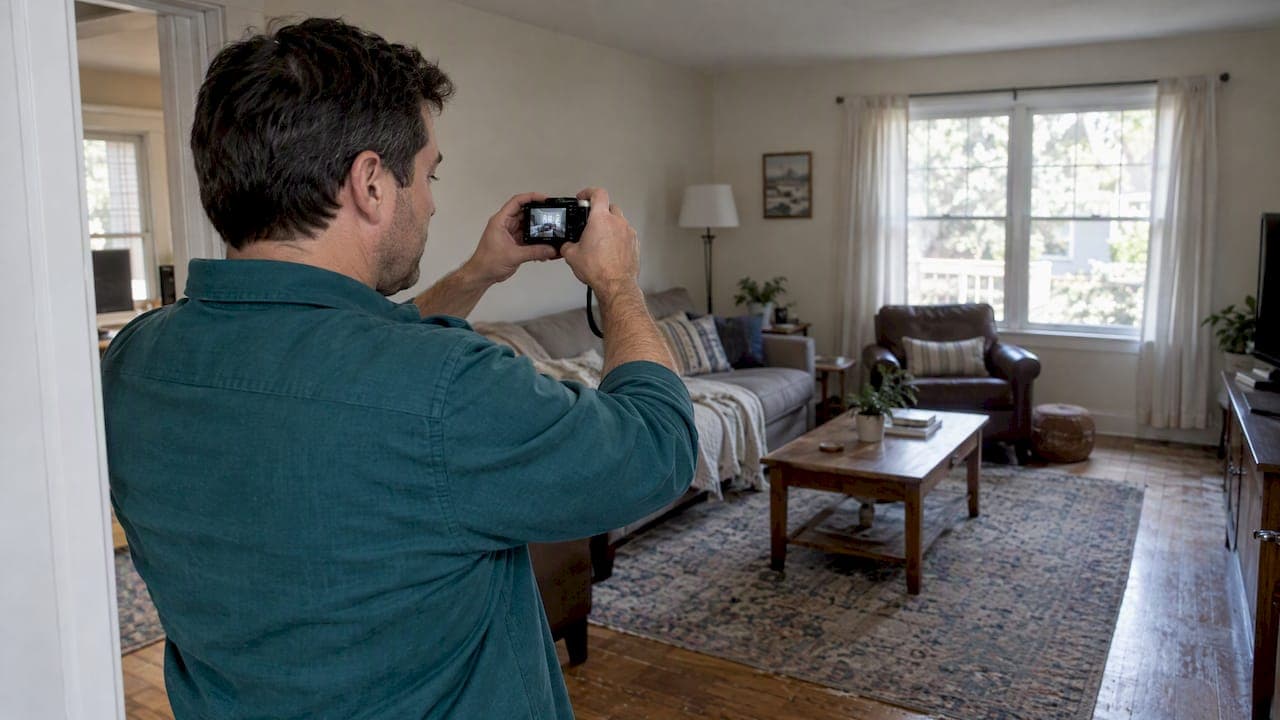
An appraisal waiver, also called value acceptance at Fannie Mae or ACE at Freddie Mac, is an automated underwriting offer that lets eligible loans close without a traditional in-person appraisal. Fannie Mae and Freddie Mac generate these offers, and they show up most often on refinances and well-documented properties. You cannot request one. At HomePilot, we help you read the offer and plan around it.
TL;DR:
- Some offers cap property value at $1 million; loan to value limits range from about 80% on purchases to 90% or 97% for certain inspection based options.
- If a pure waiver is unavailable, inspection based alternatives require a trained collector to photograph the home, record a floor plan, and gather property data.
- A waiver provides no independent opinion of value, so arrange a home inspection to catch condition problems that automated data may miss.
- Confirm that the lender will use the offer, since changed borrower or property information can revoke it and trigger an appraisal, extra days, and a fee.
Table of Contents
- How do appraisal waivers work, and who issues them?
- What property and loan traits usually qualify?
- What are the inspection-based alternatives?
- Why do borrowers and lenders like waivers?
- What do you give up when an appraisal is waived?
- What should you do once a waiver is on the table?
- A broker’s view on valuation and rates
- Check your options with HomePilot
- FAQ
- Sources
How do appraisal waivers work, and who issues them?
Both waivers come from the government-sponsored enterprises’ own underwriting engines. Fannie Mae’s value acceptance lets a lender use the submitted value when Desktop Underwriter issues an offer. Freddie Mac’s Automated Collateral Evaluation runs proprietary valuation models and collateral data, and it has expanded from refinances into eligible purchases.
Behind the scenes, the engines lean on prior appraisals, automated valuation models, and public records, as the FHFA Office of Inspector General’s overview describes. When a lender exercises an offer, it can be relieved of representation and warranty exposure on collateral value, though it remains responsible for complete and accurate property data.
One practical point: the lender can still order an appraisal anyway, and a borrower cannot force a waiver. The automated system has to produce the offer first.

What property and loan traits usually qualify?
Eligibility rules vary by program and change over time, but the pattern is consistent. Use this as a plausibility check, not a promise:
- Property type: One-unit homes, including condos, are generally in. Manufactured homes, two-to-four-unit properties, and properties with resale restrictions are often out, along with properties that require an appraisal by law, per the FHFA announcement.
- Value ceiling: Many waivers cap eligible property value at $1,000,000.
- Loan-to-value: Limits run around 80% on some purchase offers and up to 90% or 97% on certain inspection-based variants.
- Transaction type: Refinances see more offers, while cash-out transactions and certain loan features tend to be ineligible.
- Timing: Fannie Mae will not offer value acceptance when an appraisal was uploaded in the prior 120 days. An offer must also be no older than four months on the note date, according to the Selling Guide.
Changes to borrower or property data can void an offer, so a file that looks eligible on day one may not stay that way.
What are the inspection-based alternatives?
When a file does not earn a pure data waiver, inspection-based options can fill the gap. Freddie Mac’s ACE+PDR and Fannie Mae’s Value Acceptance + Property Data both rely on a trained property data collector, as HousingWire’s guide to appraisal modernization explains. The collector visits the home, captures interior and exterior data, takes photos, and records a floor plan. So even with no appraisal, someone may still walk through your house.
On the lender side, the property data goes to Fannie Mae’s Property Data API, and loans carry Special Feature Codes: 801 for Value Acceptance and 774 for Value Acceptance + Property Data, per Fannie Mae’s test case guidance. If the data raises questions, the file can be upgraded to a hybrid appraisal. In general, collecting data is faster than a full appraisal, though exact turnaround depends on collector availability.

Why do borrowers and lenders like waivers?
The upside is time and money. A waived appraisal removes the scheduling, the report, and the waiting, and borrowers typically skip the appraisal fee. Freddie Mac notes that ACE can shorten closings by multiple days.
For lenders, fewer appraisals means less tracking and more capacity. In a competitive purchase, a buyer whose file carries a waiver may be able to offer a faster, cleaner path to closing. That can help an offer stand out when sellers care about timing.
What do you give up when an appraisal is waived?
You give up an independent opinion of value. Without a third-party report, nobody outside the automated system checks market value or condition, and Redfin’s explainer flags the risk that the price paid could exceed true market value. Renovations or condition problems that the data does not capture can go unnoticed, which is why a home inspection still matters. Our guide on home inspection vs appraisal explains the difference.
A waiver is also not locked in. It can be pulled before closing if your qualification or the property data changes, and some transactions still require appraisals regardless of what the system offers. If you worry about a valuation shortfall, read our piece on appraisal gap coverage.
What should you do once a waiver is on the table?
Start by confirming what was actually issued, then ask direct questions. Here is a short list to bring to your loan officer:
- Did the underwriting system issue value acceptance or an ACE offer, and will it be exercised?
- Is property data collection required, and who schedules the visit?
- What happens to my timeline and costs if the offer is pulled?
- If I prefer a traditional appraisal, can you order one, and what will it add in time and fees?
Asking for a traditional appraisal is allowed, but expect added days and a fee. For a deeper look at how comparable sales drive valuation, this guide on running comps is a useful read.
Pro Tip: If a data collector is coming, prep the home as you would for professional listing photos: clear access to every room, utilities on, and clutter put away.
A broker’s view on valuation and rates
Most borrowers fixate on the waiver and forget the price of the loan. We think that is backward. A waiver saves days, but rate and fees decide what you pay for years. Because we price your file across 40+ wholesale lenders with $0 lender fees, we can tell you early whether a waiver is likely to hold, while you compare live rates and run your estimate through a review. Our purchases average about 20 days to close, with a 30-day commitment.
The HomePilot Team
Check your options with HomePilot

We publish live wholesale rates beside the national average every business day at our rates page, and you can get a quote without a hard credit pull. We are licensed in AZ, CA, CO, FL, and TX, with 40+ wholesale lenders and $0 lender fees. Already holding an estimate? Our loan estimate review compares it to wholesale pricing. Ready to move? Start a purchase or a refinance today.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
Can Fannie Mae waive an appraisal for a property?
Yes, when Desktop Underwriter issues a value acceptance offer and the loan and property meet program rules. The lender decides whether to use it, and Fannie Mae says value acceptance is unavailable when a recent appraisal exists in its database.
Does FHA allow appraisal waivers?
The waiver programs described here are Fannie Mae and Freddie Mac offers, so they apply to conventional loans. We would not assume an FHA loan qualifies. Ask your loan officer, or look at our FHA page for current options.
Can I ask my lender for an appraisal waiver?
No. A waiver is an automated offer produced by the underwriting system, so a borrower cannot request one. You can ask whether one was issued.
What happens if the waiver is revoked?
Your lender would typically order a traditional appraisal, which can add time and an appraisal fee. A waiver can be pulled before closing if your qualification or the property data changes.
Sources
- FHFA Announces Updates to Enterprise Policies on Appraisals, Loan Repurchase Alternatives, and Pricing Notifications | FHFA
- Automated Collateral Evaluation (ACE) - Freddie Mac Single-Family
- Value Acceptance | Fannie Mae
Recommended
- Avoid Draining Reserves: Appraisal Gap Coverage for U.S. Home Buyers
- Close in 20 Days: Home Inspection vs Appraisal for U.S. Buyers
HomePilot Mortgage, NMLS #2752340, is a licensed mortgage broker in Arizona, California, Colorado, Florida, and Texas. Equal Housing Lender. This article is general information, not a loan offer or a commitment to lend. Rates and program terms change daily and depend on credit, loan amount, and county. HomePilot Mortgage is a private company, not affiliated with or endorsed by the Department of Veterans Affairs, HUD, or any government agency.